AI Companies We Support
Ridgeway Financial Services is a CPA-led firm that provides accounting, bookkeeping, fractional CFO leadership, and audit readiness for AI companies. We serve companies whose economics are shaped by AI: revenue that is priced on usage, tokens, or outcomes rather than seats; gross margin that rises and falls with compute; large portions of spend in research, data, and model access that demand capitalization judgment; and tax outcomes that depend on documenting all of it.
Is this service for you? If AI changes your revenue model or your cost structure, meaning usage or outcome pricing, meaningful inference cost, or real capitalization decisions on models and data, you are an AI company and this page is for you. If AI is a feature on a seat-based software product with trivial inference cost, our technology and SaaS accounting page will serve you better.
Who We Serve in AI
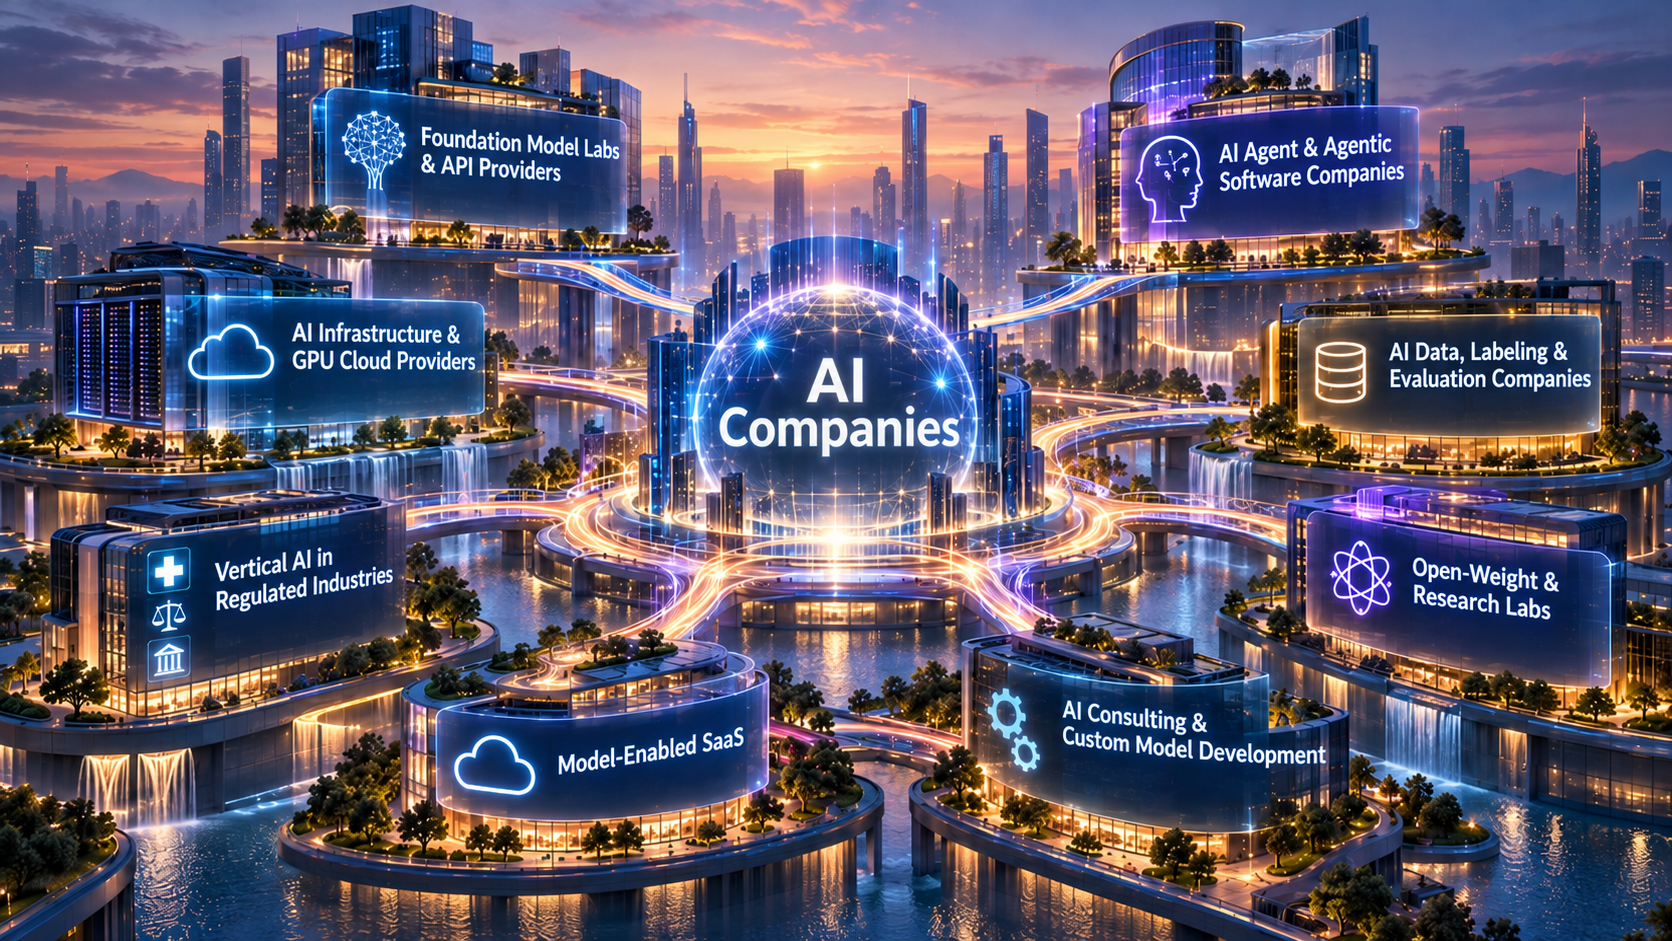
We work across the full range of AI business models, from foundation model labs to companies adding a real AI product line. Each link below leads to a guide on the accounting issues specific to that model.
- Foundation model labs and API providers (inference cost of revenue, token margin, prepaid credits, enterprise minimum commits)
- AI agent and agentic software companies (outcome-based and per-task pricing, usage credits, variable consideration)
- AI infrastructure and GPU cloud providers (hardware capitalization and depreciation, GPU financing, utilization economics)
- AI data, labeling, and evaluation companies (data as cost of revenue or intangible, annotation labor, contractor reporting)
- Vertical AI in regulated industries (healthcare, legal, and financial-services AI with industry revenue and compliance overlays)
- Model-enabled SaaS adding AI product lines (bundle allocation, AI add-on pricing, margin compression from inference cost)
- AI consulting and custom model development (services revenue, milestone and fine-tuning engagements, IP ownership)
- Open-weight and research labs commercializing models (development cost capitalization, licensing models, grant and non-dilutive funding)
What We Deliver
Fractional CFO leadership for AI companies
Stage-appropriate fractional CFO scope built for AI economics: driver-based compute forecasting, unit economics and gross margin by model and customer, pricing and packaging that protect margin, fundraising models and board reporting, and capital strategy including cloud commitments and GPU financing. See our fractional CFO service page, the AI CFO guide, and our GPU cost forecasting and AI unit economics guide. Size an engagement with the fractional CFO cost estimator.
Accounting and bookkeeping for AI operations
- Revenue recognition for usage-based APIs, prepaid credits, minimum commits and overages, and bundled AI services under ASC 606
- Deferred revenue, prepaid credit liabilities, and breakage schedules tied to usage logs
- Compute cost allocation across inference, training, internal tooling, and overhead using cloud billing exports and tags
- Foundation-model fees, cloud commitments, and prepaid credits accounted for by arrangement substance, not invoice format
- An AI-specific chart of accounts and monthly close that keeps compute, data rights, and deferred revenue visible
- AI KPI reporting: cost per inference, compute as a percent of revenue, gross margin by model, and burn sensitivity to compute
- Multi-entity consolidation, intercompany, and FX for groups whose core value is model IP
- For broader scope, see our accounting and bookkeeping services and the bookkeeping cost estimator
Capitalization policy and R&D tax
- AI development cost decisions across ASC 730, ASC 350-40, and ASC 985-20, with a documented decision framework
- Training data and dataset license treatment based on project stage, intended use, and alternative future use
- Section 174A domestic research deductions, Section 174 foreign research amortization, and the Section 41 credit including the payroll offset
- Business-component records, wage and contractor mapping, and data-cost support for Form 6765
- A clean bridge between GAAP R&D, tax R&D, and capitalized software so the credit study is faster and stronger
- Non-dilutive funding support, including SBIR and STTR for AI research companies
Controls, audit readiness, and diligence
- Audit documentation for capitalized AI costs, including the workpapers auditors test
- Controls over the operational data that drives the books: usage-log completeness, cloud-tag hygiene, and price-source governance
- Internal controls over AI systems used in financial reporting and AI risk disclosure and board oversight for companies approaching public-company standards
- SAFE, convertible note, 409A, and stock compensation hygiene inside the monthly close rather than at year-end
- Technical accounting memos for capitalization, data rights, foundation-model arrangements, and revenue
- The AI data room: compute commitments, gross margin by model, and capitalization support investors ask for. See our fundraising data room checklist
Why Ridgeway Financial Services
- A dedicated AI practice, not a SaaS template. Usage-based revenue, compute-driven margin, capitalization judgment, and R&D tax substantiation are the core of the engagement, not add-ons.
- CPA credentials with Big Four backgrounds. Audit, technical accounting, and finance leadership experience applied to models, data, and compute rather than only subscriptions.
- Built for the intersections. We also run dedicated fintech and crypto practices, so an AI lending platform or an AI company with a token gets one team that understands both sides.
- The deepest published AI accounting library of any firm our size. Our AI accounting and finance guides cover revenue recognition, development costs, training data, GPU economics, audit documentation, controls, and disclosure, and they are the same frameworks we apply for clients.
- Integrated service scope. Fractional CFO, accounting, capitalization and tax policy, and audit readiness operate as one engagement that scales from Seed through Series B and beyond.
- Embedded, not outsourced. We work inside your finance function and coordinate directly with your tax CPA, auditors, counsel, and cloud and billing vendors.
Frequently Asked Questions
What does an accounting firm for AI companies do differently?
It operates the finance function around AI economics: recognizing usage-based and prepaid-credit revenue correctly, allocating compute between cost of revenue and R&D, deciding what gets capitalized across models, software, and data, substantiating R&D tax positions, and producing the gross margin and KPI reporting AI investors expect. A generic startup firm typically books all cloud spend to one line and treats every contract like a subscription.
What types of AI companies does RFS serve?
Foundation model labs and API providers, AI agent companies, AI infrastructure and GPU clouds, data and labeling companies, vertical AI in regulated industries, model-enabled SaaS with real AI product lines, AI consulting and custom model developers, and open-weight or research labs commercializing models.
How should an AI company account for GPU and cloud compute?
Compute that directly fulfills customer requests in the current period generally belongs in cost of revenue. Compute aimed at improving future models or products generally belongs in R&D unless it qualifies for software capitalization, and internal tooling is assessed under ASC 350-40. That only works if the books mirror cloud telemetry, so we split compute by inference, training, internal tools, and overhead using billing exports and tags. See our GPU cost guide.
Can AI development and training data costs be capitalized?
Sometimes. Most exploratory AI research is expensed under ASC 730. Internal-use software can be capitalized under ASC 350-40 once the threshold is met, and software to be sold can be capitalized under ASC 985-20 after technological feasibility. Licensed data with alternative future use is generally capitalized; data acquired solely for one R&D project is expensed. We document each decision so it holds up in audit. See our guides on AI development costs and training data.
Do AI companies qualify for R&D tax credits?
Often, yes. Model development, experimentation, and much data work can qualify as research under Section 41, and qualified small businesses can apply part of the credit against payroll taxes. Under current law, domestic research expenditures are generally deductible under Section 174A while foreign research remains amortized under Section 174, so the domestic-versus-foreign split in your books matters. Form 6765 now requires business-component detail, which is why we keep project-level records all year. Our AI bookkeeping guide covers the tax bridge in depth.
How does engagement with RFS work?
Engagements begin with a scoping conversation about your stage, revenue model, and compute footprint. We then propose a structure that may include fractional CFO scope, accounting and bookkeeping, capitalization and tax policy projects, or audit readiness. Most engagements are monthly retainers, with project-based work for specific deliverables. The fractional CFO, fractional controller, and bookkeeping cost estimators give a quick read before we talk.
Does RFS work with audit firms and investors?
Yes. We prepare audit-ready documentation for capitalized AI costs, revenue, and data rights, respond to auditor requests, draft technical accounting memos, and serve as the day-to-day audit liaison. For fundraising, we build the data room and the gross margin and compute story investors diligence in AI companies.